Inderes uses cookies to provide a better user experience and a personalised service. By consenting to the use of cookies, we can develop an even better service and will be able to provide content that is interesting to you.
Björn Borg operates in the fashion industry and focuses on the design, manufacture and distribution of sportswear and underwear, accessories and bags. The company's products are aimed at men, women and children of all ages. The business is global with a main presence in the Nordic region and Europe. Björn Borg was founded in 1984 and has its headquarters in Solna.
Björn Borg's Q3 report beat our expectations, with strong profitability driven by a favorable channel mix. Given the attractive combination of expected earnings growth and a high dividend yield, we continue to see the stock's risk/reward ratio as attractive.
Join Inderes community
Don't miss out - create an account and get all the possible benefits
FREE account
Stock market's most popular morning newsletter
Analyst comments and recommendations
Stock comparison tool
PREMIUM account
All company reports and deep analyses
Premium tools: model portfolio, screener, insider transactions
Premium columns: Guest column, expert insights
Inderes MCP - Inderes data directly into your AI tools
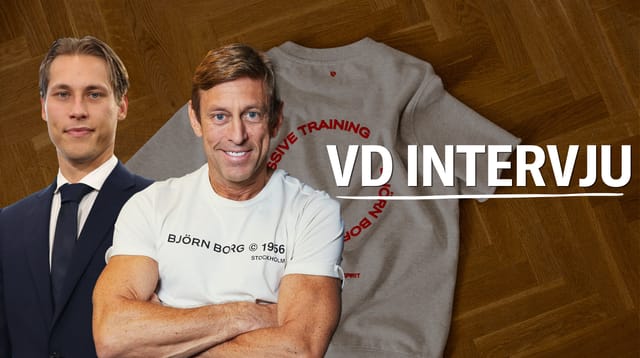
Björn Borg reported Q3'26 on October 23, showing a strong quarter where proprietary e-commerce drove both growth and profitability. CEO Henrik Bunge joins us today to share his view on the quarter.
We have taken a more cautious stance on our near- and mid-term revenue estimates due to weaker consumer sentiment and a less supportive macro environment, particularly in continental Europe. Despite these downward revisions, we believe that the current valuation offers an attractive risk/reward profile, as the share price has fallen by around 15% since our last update.
We continue to see good opportunities for the company to get back on track and deliver profitable growth and solid value creation. As a result, we continue to view Björn Borg as an interesting investment opportunity, given the attractive combination of expected earnings growth and dividend yield.
We expect the company to deliver solid revenue growth, primarily driven by the sports apparel category and its own e-commerce, while the underwear segment normalizes after a strong Q1.
In our view, Björn Borg has made good progress executing its strategy of expanding its core product categories and own e-commerce channel, which we expect to keep driving profitable growth.